
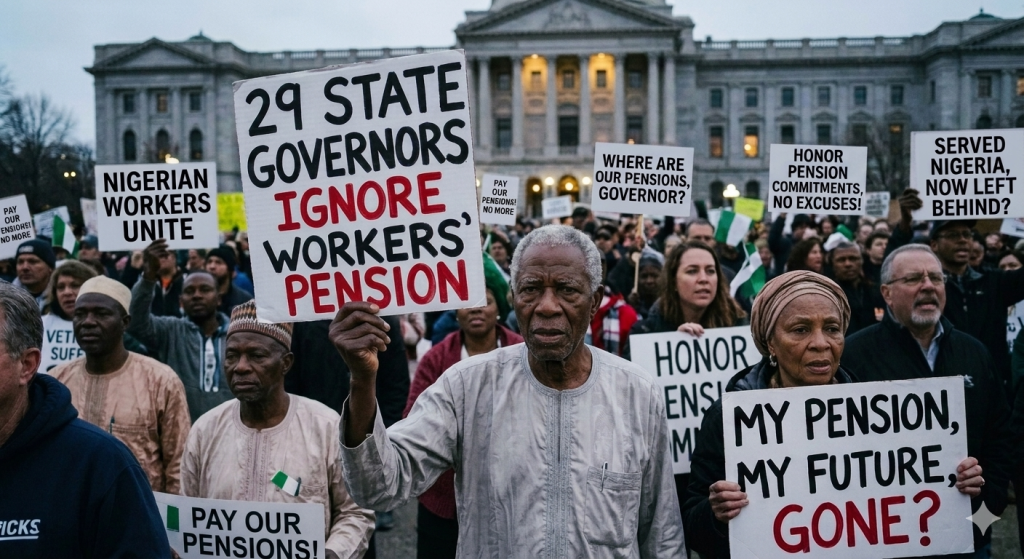
29 State Governors Ignore Workers’ Pensiion
….As Pension Backlogs In States Mount
BY ZAKA KHALIQ and CEES HARMON
No fewer than 29 State governors have ignored the pension benefits of their workkers, leaving them to have a bleak future in retirement, BUSIINESSDIARY can now reveal.
While 17 States have domesticated the new pension law in their respective State, they are still yet to implement this, leaving their workers with a bleak future in retirement. Another 11 States are, however, implementing but are not contributing as and when due.
Abia, Adamawa, Bauchi, Bayelsa, Ebonyi, Enugu, Gombe, Imo,Kano, Katsina, Kebbi, Kogi, Nasaraw,a Niger, Ogun, Oyo, Plateau, Rivers, Sokoto, Taraba, Yobe and Zamfara States have domesticate the law but have not make any meaningful contributions.
Akwa Ibom, Borno, Cross-River, Katsina, Kwara and Plateau States are at the legislative level and are yet to enact the necessary bills into law.
According to the Pension industry 4th Quarter Report 2025 released recently by the National Pension Commission (PenCom) , only 8 States have so far fully compliant with the Contributory Pension Scheme (CPS) while Kano State is implementing pension plans but outside the jurisdiction of the Pension Fund Administrators(PFAs).
The report stated that “only eight States are fully compliant with the CPS. A further 17 States have passed pension reform legislation but have not yet moved to implementation; a population that
should now be the principal focus of bilateral compliance engagement.
“Jigawa State runs a fully implemented Contributory Defined Benefits Scheme. Kano State, despite progress on enabling legislation, is operating outside the regulatory architecture: its pension funds are still held with commercial banks rather than being placed under licensed Pension Fund Administrators.”
The 8 fully-compliant States include; Lagos, Kaduna, Edo, Ondo, Ekiti, Osun, Jigawa States and Federal Capital Territory (FCT).
Confirming this development, director-general, PenCom, Omolola Oloworaran, stressed the need for stronger commitment by states to pension reforms.
She noted that, although many states had enacted pension laws in line with the Pension Reform Act, implementation remained weak in most parts of the country.
The discussions, according to the commission, focused on practical support mechanisms, the benefits of the CPS and ways of overcoming challenges slowing adoption at the state level.
Although, there is no official data on how much pension backlog these States were owing, industry source put the arrears to about N300billion, as at the end of 1st quarter of 2026.
Market observers and experts are,however, raising concerns over the failure of several state governments to remit pension deductions into the Retirement Savings Accounts (RSAs) of civil servants, a development they warned could plunge thousands of workers into financial hardship in old age and undermine confidence in Nigeria’s contributory pension system.
Under the Pension Reform Act (PRA) 2014, employers and employees are required to make monthly pension contributions of at least 10 per cent and eight per cent of an employee’s monthly emoluments respectively into workers’ RSAs managed by Pension Fund Administrators (PFAs).
However, despite deducting pension contributions from workers’ salaries, many state governments have either failed to remit the funds altogether or have accumulated years of pension arrears, according to industry stakeholders.

“Every month that pension contributions are not remitted represents a loss of retirement income for workers because those funds are not being invested on their behalf,” a pension industry analyst, Mr. Paul Okpere, told this medium.
According to him, the consequences become more severe over time as workers lose the benefit of compound returns that form the foundation of the contributory pension system.
Labour unions have also expressed concern over the situation.
The Nigeria Labour Congress (NLC) has on several occasions accused some state governments of deducting pension contributions without remitting them, describing the practice as a breach of trust and a violation of workers’ rights.
“Many workers only discover the extent of the problem when they are approaching retirement and realize that years of deductions were never credited to their accounts,” said a labour leader who preferred not to be named.
Pension operators warned that the situation could create a new generation of elderly Nigerians without adequate retirement income.
For a civil servant who spends 30 to 35 years in service, pension contributions and investment earnings are expected to provide a financial cushion after retirement. Where remittances are delayed or not made at all, retirees may receive significantly reduced benefits or face lengthy verification and recovery processes.
The chief executive at the Center for the Promotion of Private Enterprise (CPPE), Dr. Muda Yusuf, noted that pension security is critical not only for retirees but also for economic stability.
“When workers are uncertain about their retirement future, it affects morale, productivity and confidence in public institutions. Pension obligations should be treated as a first-line charge by governments.
“The contributory pension scheme is one of Nigeria’s most successful financial sector reforms. But its success can only be sustained if every kobo deducted from workers is remitted promptly and transparently,” he said.
The challenge is particularly worrying against the backdrop of rising inflation and the increasing cost of living. Analysts said, retirees without adequate pension savings could face difficulties meeting basic needs such as healthcare, housing and food.
Some state governments have attributed the problem to fiscal constraints, declining revenues and competing expenditure demands. However, experts argue that pension deductions belong to workers and should not be used to finance government operations.
To address the growing menace, stakeholders are calling for stronger enforcement measures by PenCom and other regulatory agencies.
Among the recommendations is the imposition of sanctions on defaulting states, including restrictions on access to certain federal interventions and borrowing facilities until outstanding pension remittances are settled.
Experts also advocate greater transparency through the publication of state-by-state pension compliance records, enabling workers and the public to monitor remittance performance.
Financial economist at Nnamdi Azikiwe University, Dr. Felix Echekoba, called for the establishment of dedicated pension remittance accounts insulated from political interference, the automation of pension deductions and transfers and the strengthening of legislative oversight at the state level.
He said the long-term sustainability of Nigeria’s pension system depends on strict compliance with remittance obligations.
As pension assets continue to grow nationally, stakeholders insist that protecting workers’ retirement savings must remain a priority to prevent today’s public servants from becoming tomorrow’s pensioners in distress.





