
Digital Lending Can Unlock Credit Access, Drive Nigeria’s Economic Growth – Osuchukwu
BY ZAKA KHALIQ
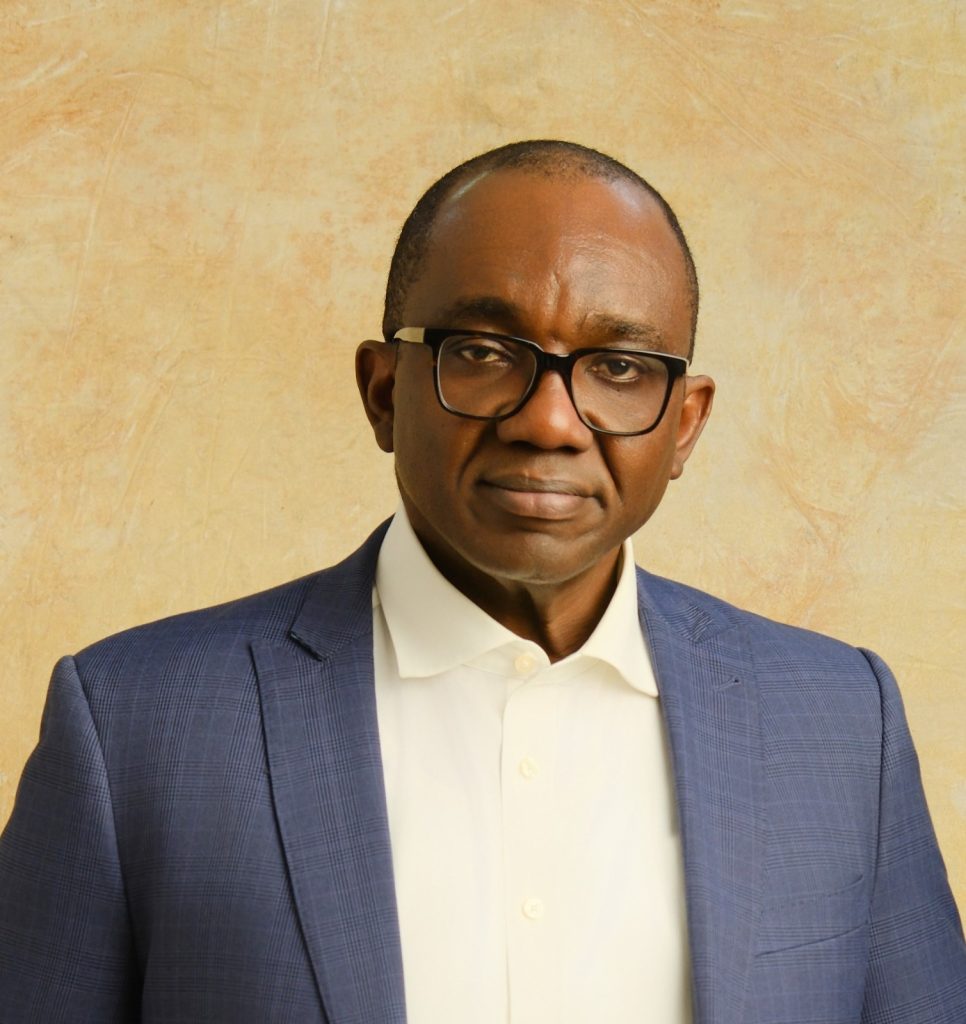
Digital lending has the potential to bridge Nigeria’s persistent credit gap, expand financial inclusion and accelerate economic growth by providing small businesses and informal-sector operators with access to affordable working capital, founder and chief executive officer(CEO)! of Mathesis Analytics, Winston Osuchukwu has said.
Osuchukwu said, although Nigeria had made significant progress in financial inclusion, with 73 per cent of adults formally included, access to financial services had yet to translate into meaningful credit opportunities for millions of individuals and micro-enterprises.
Citing EFInA’s 2026 Access to Financial Services survey, he noted that the proportion of Nigerian adults borrowing from banks and other licensed lenders increased from six per cent in 2023 to 10 per cent in 2026, leaving the overwhelming majority without access to formal credit.
In an article titled ‘The Potential for Digital Lending to Drive Inclusion and Economic Growth,’ Osuchukwu identified traditional lending requirements, including physical collateral, payslips and audited financial records, as major barriers preventing informal businesses from accessing institutional financing.
He argued that, although many small-business operators have the capacity to repay loans, conventional lenders lack the information and tools to properly assess their financial activities, particularly, as their transactions are often scattered across mobile wallets, bank accounts and cash-based operations.
According to him, this credit gap is restricting business expansion, weakening productivity and limiting the broader economic benefits that could come from adequately financing Nigeria’s informal sector.
Illustrating the consequences, Osuchukwu said, market traders often struggle to increase inventory during peak-demand periods because they lack the working capital to purchase additional stock.
Similarly, tailors and other small-scale entrepreneurs are unable to acquire additional equipment or employ more hands to meet rising demand, forcing them to turn down business opportunities and surrender potential revenue to competitors.
He warned that, the inability to secure affordable institutional credit pushes many operators towards informal lenders charging exorbitant interest rates, which erode profit margins and trap businesses in a cycle of expensive borrowing.
While savings arrangements such as Ajo provide some financial support, he said their limited capital and fixed payout schedules often make them unsuitable for businesses facing urgent financing needs.
Digital lending offers alternative

Osuchukwu said digital lending could address these challenges by enabling financial institutions to assess borrowers through alternative data, rather than relying exclusively on conventional credit requirements.
He explained that, transaction records from mobile wallets, agency banking networks, bank accounts and utility payments could provide valuable insights into business revenue patterns, cash flows and repayment capacity.
By analysing these verifiable financial footprints, digital lenders, he said, can identify creditworthy individuals and businesses that traditional lending models routinely overlook.
He identified deeper credit inclusion and increased business productivity as two major benefits of this approach.
According to him, borrowers accessing formal credit for the first time can gradually build credible repayment histories, enabling lenders to increase their credit limits and offer more competitive interest rates as their relationships mature.
At the wider portfolio level, accumulated repayment data would also enable lenders to assess risks more accurately, improve loan pricing and potentially reduce borrowing costs for subsequent applicants, he pointed out.
Osuchukwu added that, affordable working capital would allow small businesses to purchase inventory in bulk, acquire better equipment, employ additional workers and respond more effectively to market demand.
Economic growth multiplier
He maintained that the broader economic significance of digital lending lies in its ability to expand credit access while simultaneously strengthening the productive capacity of micro-enterprises and small businesses.
According to him, adequately financing informal businesses would stimulate job creation, increase national productivity and direct capital towards economic activities capable of generating significant multiplier effects.
“When millions of informal operators are given the capital to upgrade from basic survival to active expansion, the effects extend far beyond their individual businesses,” he argued.
He said, the resulting expansion in business activities could also strengthen the country’s tax base, deepen economic participation and unlock growth opportunities across local communities.
Osuchukwu stressed that, digital lending should therefore be viewed not merely as another financial technology innovation, but as a strategic instrument for unlocking the productive potential of Nigeria’s largely underserved small-business sector.
He maintained that making credit more accessible and affordable could transform financial inclusion from simply giving people access to accounts and payment services into providing the capital they need to grow businesses, create jobs and contribute more meaningfully to the economy.





